
Most finance leaders at consumer brands have already tried AI on their numbers. Paste in a P&L, ask a question, get an answer. Ask again, get a different one. As one operator put it on a recent call, "I don't trust it yet." That is a fair place to land, and it is not the AI's fault.
AI agents in finance are software that does finance work on its own: they query a live financial model, draft the "what changed and why" for each line, watch for anomalies, and build scenarios from a sentence of instruction. The difference between an agent you trust and a chat window you double-check is not the model. It is the data underneath it.
SEEQ, a supplement brand selling across Shopify, Amazon, TikTok Shop, and Target, went from forecasts that took two to three days to answers that arrive instantly, on numbers the team had already vetted. This post covers what AI agents actually do for a consumer brand finance team, where the adoption-to-value gap comes from, and what has to be true before you hand an agent the keys.
What AI agents in finance actually are (and what they are not)
An AI assistant answers from what you give it. You paste a spreadsheet, ask a question, and it reasons over that one file for that one session. Close the window and it forgets everything.
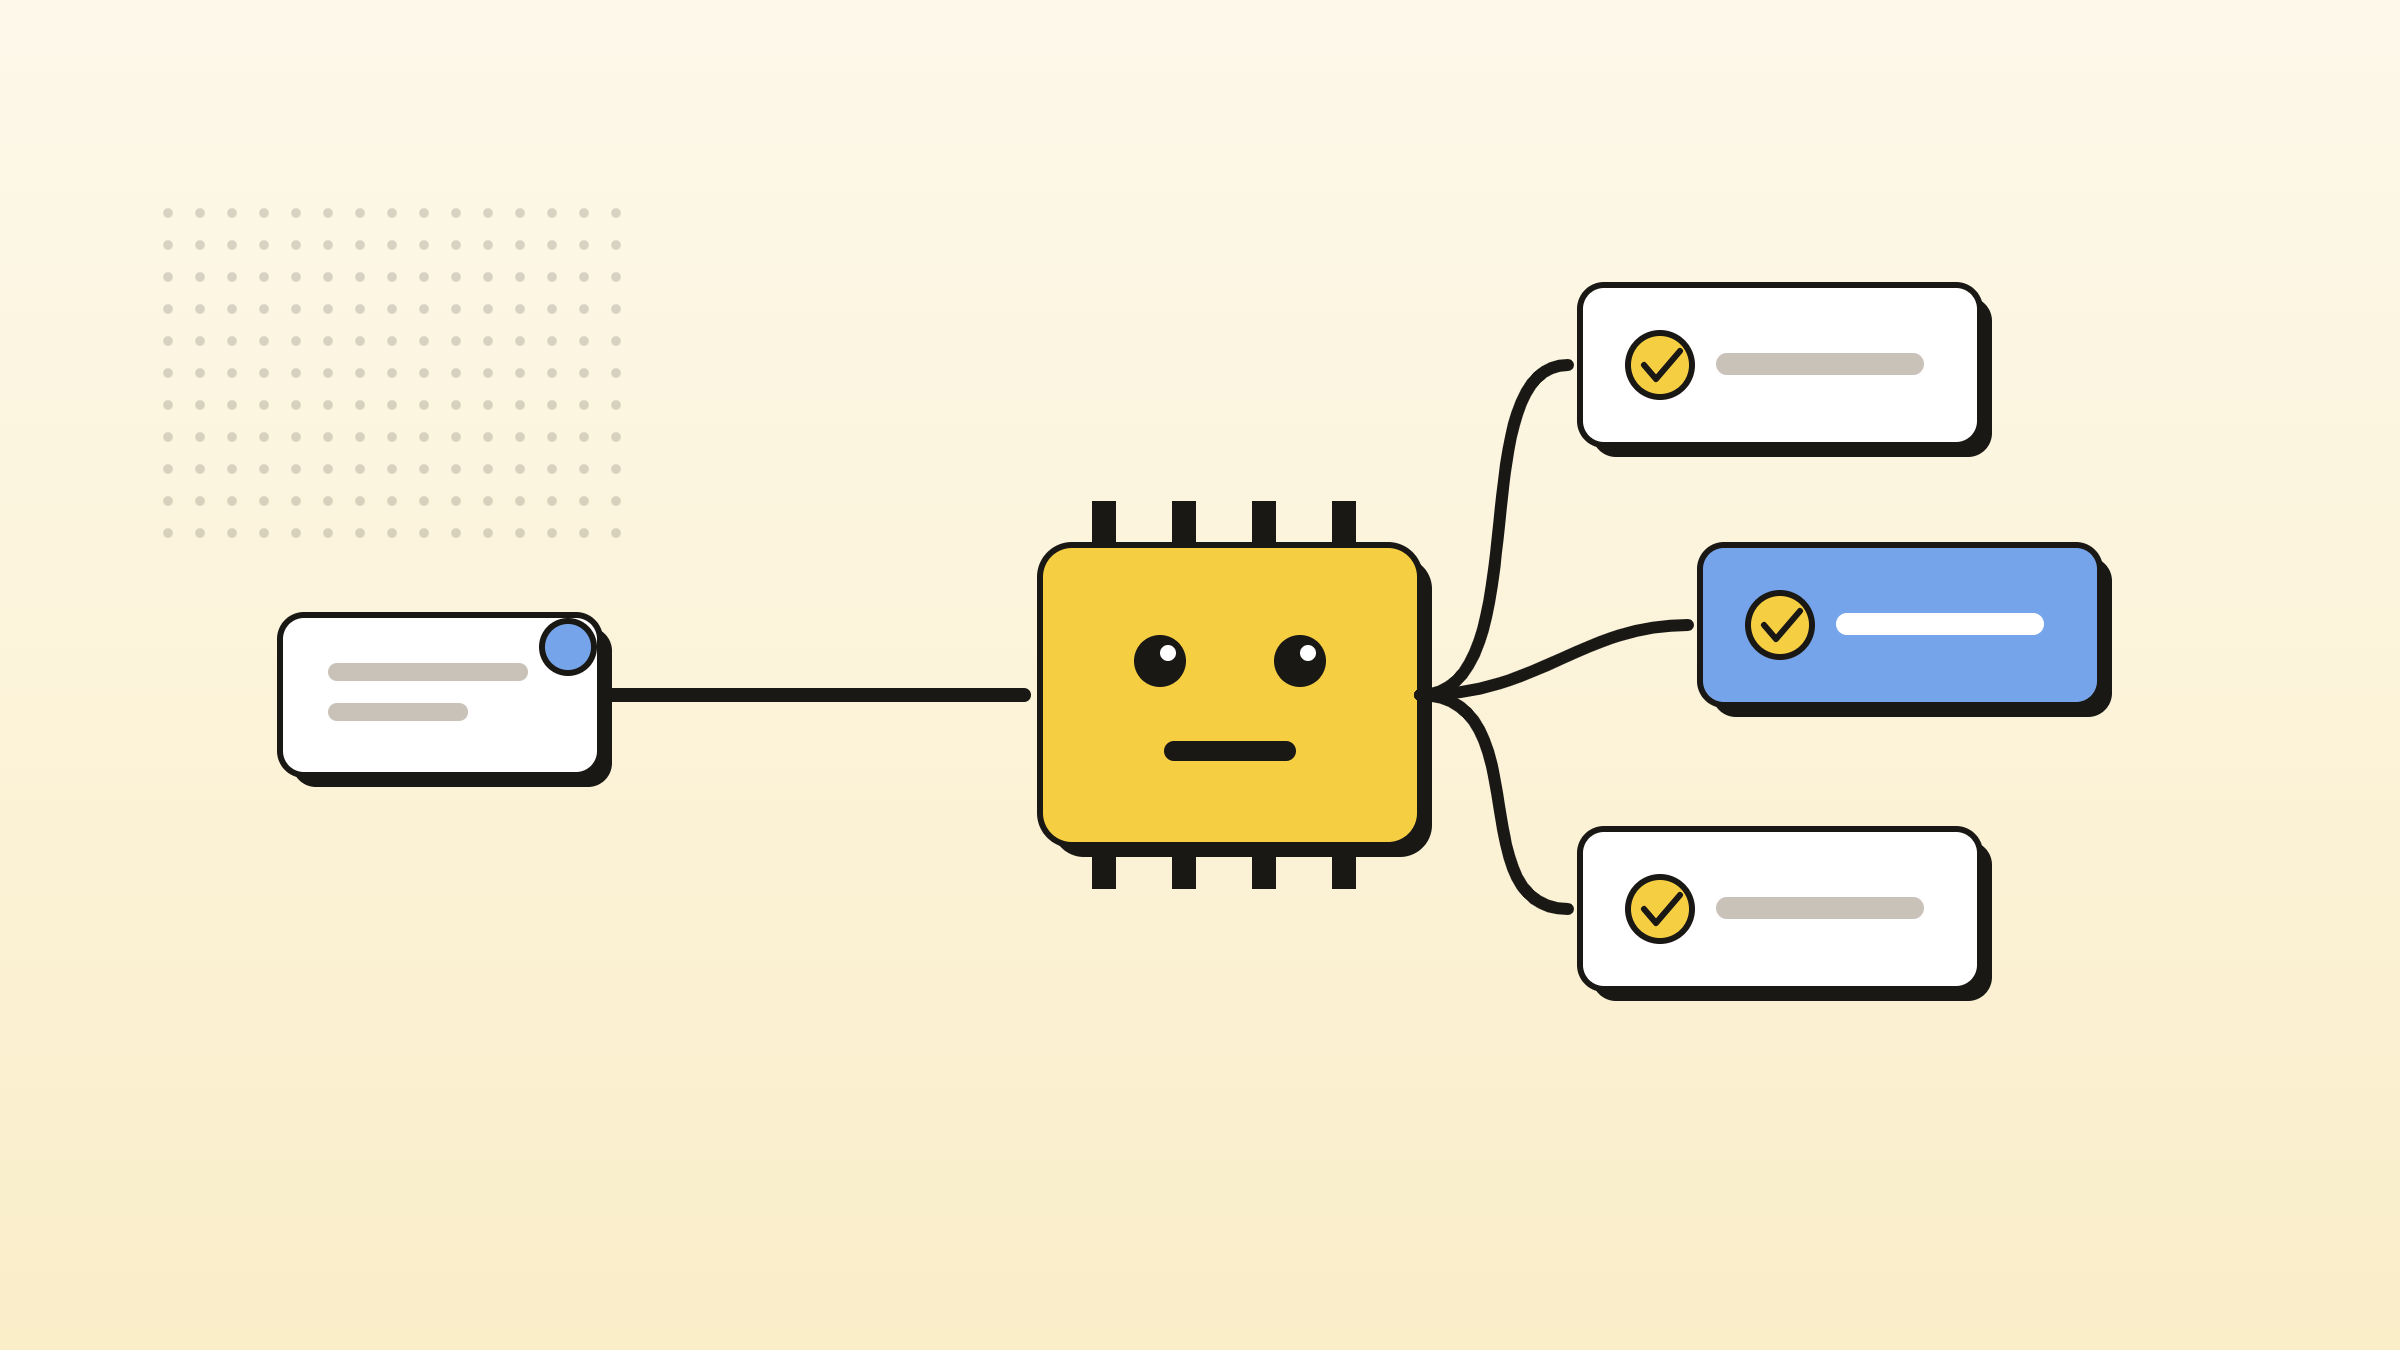
An AI agent has standing access to your financial model and the data behind it. It can take actions: run a query, draft a paragraph, fire an alert, branch a scenario. And it shows its work, citing the cells or tables it pulled from so you can check it.
For a consumer brand FP&A team, agents do four jobs. They answer. They draft. They watch. They build. The next section takes each one in turn.
First, the trust problem, because it is the reason most finance teams stopped at the assistant stage. Ask a general-purpose model the same question several times and you can get several answers. That is not a bug in the model. It is what happens when a model reasons from general knowledge and has to re-learn your business every session. Every team has access to the same models now. What separates outcomes is what the model is allowed to touch.
What can AI agents do in finance? Four jobs for a consumer brand FP&A team
Answer. Plain-English questions against the live model. "Why did Q3 contribution margin drop?" "Which SKUs are about to stock out?" "What was Amazon CAC last week versus the trailing eight?" The agent queries the model, returns the number, and cites the cells it used. Compare that to the old path: file a request, wait two days for an analyst to look into it, get an answer after the meeting where you needed it.
Draft. At month-end, the agent writes the first pass of variance commentary for every line: sales, gross margin, opex, cash. You edit, accept, and send. Over time it learns your house tone and the framings your board cares about. Reporting goes from a blank page to a twenty-minute review.
Watch. Always-on monitors track anomalies, threshold breaches, connector health, and data quality around the clock. When Meta CPMs jump 38% or a connector goes stale, the alert lands in Slack with context and a suggested action. The first sign of drift shows up the same day, not in next month's board pack.
Build. Describe a scenario in a sentence: "Flat DTC, wholesale down 20%, hold opex." The agent branches the model, sets the drivers, runs the math, and hands back a side-by-side against the base case. You review every assumption before it lands. Tweak it, save it, or throw it away.
These four jobs sound generic until you ask what the agent needs to know to do them for a consumer brand. It has to understand retail deductions and trade spend. It has to separate new customers from returning ones across Shopify and Amazon. It has to reason about SKU-level demand and channel-level margin, not just a single revenue line. A bank's fraud-detection agent does not know any of that. An agent built for consumer brands does, because those skills ship with it.
SEEQ's finance function used to live in ad hoc Google Sheets, updated quarterly at best, with everything 30 to 60 days in the past. Testing a Black Friday spend threshold meant duplicating workbooks and hoping the assumptions held. Now scenarios run in a few clicks against the baseline, and the team used that speed to redesign its entire Shopify strategy, dialing in subscription take rates, AOV targets, and CAC thresholds. As CEO Keenan Kelly put it: "Drivepoint is a central, reliable source of truth. I don't have to wait for anybody."
Old way vs. new way: what changes in a real finance workflow
The clearest way to see what agents change is to put one workflow side by side.
| Workflow | Old way | New way | What the human still does |
|---|---|---|---|
| Monthly variance commentary | Analyst pulls exports, builds the bridge, writes every line from scratch. Days. | Agent drafts commentary per line in the house tone. Minutes. | Edits, adds judgment, accepts, sends. |
| Board-ready reporting | Weeks of prep; version control by email. SEEQ waited on a 30 to 60 day lag. | Reports pull from the live model. Lalo went from weeks of prep to same-day board readiness. | Decides what the numbers mean and what to ask the board for. |
| Ad hoc scenario | Clone the workbook, rebuild drivers, reconcile. Lalo's founders spent 40 to 60 combined hours per forecast cycle. | One sentence branches the model. Lalo now re-rolls a full forecast in 3 to 4 days, a 97% reduction from months. | Reviews assumptions, picks the case, makes the call. |
Notice that the work does not disappear. It moves. From building the model to reading the answer. From assembling the board package to deciding what it means. Lalo's board asked for both a conservative and an aggressive case; the founders delivered both with full detail in days and, in co-founder Gregory Davidson's words, "barely even needed FP&A help." The board signed off within a day.
The outcome when the model is trusted enough to run the business on looks like Laundry Sauce: 98% forecast accuracy, $12,000 saved annually on financial management, and 10 hours back every month, after consolidating Shopify, Amazon, and QuickBooks into one model that CEO Ian Blair manages himself.
Why most finance AI projects stall (the adoption-to-value gap)
The industry data tells a consistent story: adoption is up, value is lagging.
- Gartner's March 2026 survey of 204 finance leaders, presented in May 2026, found that 63% of finance organizations said AI implementation was slower than expected in 2025, and financial forecasting and insight generation were among the lowest-rated use cases for impact.
- Deloitte's 2026 Finance Trends report found that among the 63% of organizations with fully deployed AI, only 21% believe those investments have delivered tangible value, and just 14% have integrated AI agents directly into the finance function.
- PwC's 2025 AI Agent Survey found 79% of executives say agents are being adopted at their companies, but only 34% are using them in accounting and finance.
Why does the function with the most structured data in the company struggle to get value from AI? In operator terms, the causes are familiar. The data is raw and unreconciled. The same SKU has a different name in every channel. The model has to be re-uploaded every session. And when an answer comes back, there is no lineage from the number to its source, so someone has to check it by hand. As one prospect described the experience: "You have to really be careful and check everything."
The fix is unglamorous. Put a clean, vetted data layer underneath the agent: raw, cleaned, segmented, finished. The agent queries the finished layer, so it reproduces the right number instead of inventing one. Every answer traces back to its source. Do not bring the data to the model. Bring the model to the data.
The same architecture answers the security question. Your data works only for you: it is isolated to your instance, not used to train shared models, and covered by row, tab, and scenario-level permissions with a full audit trail. An agent that can see your entire P&L should only answer within the boundaries your team sets.
Laundry Sauce's Ian Blair summed up the stakes: "If your model isn't that accurate, and you're looking three months into the future, you're living in fantasy land." An agent on bad data gets you to fantasy land faster.
How to put an AI agent to work on your numbers
A crawl, walk, run path works better than a big-bang rollout.
Crawl: fix the data first. Connect Shopify, Amazon, retail, and your accounting system (QuickBooks or NetSuite) into one source of truth that actualizes daily. Do not start with the AI. Start with the data it will touch. If the numbers do not match what you know is true, no agent will fix that.
Walk: turn on answering and drafting. Let the team ask questions and let the agent draft variance commentary. For the first month, verify answers against the model live until the team trusts them. Trust is earned one cited answer at a time.
Run: turn on watching and building. Set anomaly and threshold monitors in plain English. Build scenarios from a sentence. Then open the same data layer to marketing, ops, and the CEO, so the questions stop bottlenecking on finance.
Whatever you evaluate, require five things: cited sources on every answer, persistent context so you never re-upload your model, pre-built consumer-brand finance skills, Excel continuity so your team keeps working where it already works, and published pricing.
Drivepoint's AI agents for finance teams do the four jobs above on a vetted data layer built for consumer brands, and you can ask your numbers anything in Claude through the MCP server. If you want to feel the difference before connecting your own data, try it on a sample brand in Claude. It takes about five minutes, with no setup and no sales call.
For the longer argument on why the system around the model matters more than the model, read Finance Is Having Its Cursor Moment and Stop Preparing to Answer Questions.
AI agents in finance: common questions
What can AI agents do in finance?
For a consumer brand finance team, AI agents do four jobs. They answer questions from the live financial model in plain English and cite the cells or tables they used. They draft variance commentary for every line at month-end. They watch the data around the clock for anomalies, threshold breaches, and broken connectors. And they build scenarios from a one-sentence instruction, branching the model so you can compare outcomes side by side. In every case a human reviews and accepts the output before it goes anywhere.
Which AI agent is best for finance at a consumer brand?
The right agent is the one that runs on your vetted data rather than on whatever you paste into a chat window. Look for four things: every answer cites its source, the agent keeps persistent context so you are not re-uploading your model each session, it ships with consumer-brand finance skills (retail deductions, new versus returning customers, SKU-level demand, multi-channel margin), and it works inside Excel and the tools you already use. Drivepoint's agents are built specifically for consumer brands and connect to Shopify, Amazon, retail, NetSuite, and QuickBooks.
Will an AI agent make up numbers?
A general-purpose model pointed at raw, unreconciled data will. It reasons from general knowledge and can confidently invent a channel or a margin. The fix is architectural, not a better prompt: the agent should query a clean, finished data layer and reproduce the number that is already there, then show its source so you can verify it against the model live. That is how Drivepoint's agents are designed, and it is why the answer can be acted on instead of double-checked for an hour.
What is the difference between an AI agent and using ChatGPT or Claude directly on my financial data?
Using Claude or ChatGPT directly, you paste in data, ask, and re-teach the model your business every session. It has no live connection to your systems, no memory of your model between conversations, and no domain skills for consumer brand finance. An agent has persistent access to your vetted data, understands your model structure, takes actions (drafting, monitoring, building scenarios), and cites its sources. Claude is the engine; the agent and the data layer around it are the car. Drivepoint works with Claude, ChatGPT, and Gemini, so the model is your choice.
Can AI agents replace a finance analyst or a fractional CFO?
They replace the mechanical part of the job, not the judgment. Rolling the forecast forward, drafting variance commentary, monitoring data quality, and answering ad hoc questions from the model are the hours an agent takes over. What remains is interpretation, business partnering, and the calls only a person can make. In practice, a lean team of one or two people on Drivepoint covers what previously took a larger team, and a fractional CFO spends their hours on strategy instead of spreadsheet maintenance.